OFW Abroad: A Safer Guide to Philippine Content, Remittances, and Accounts
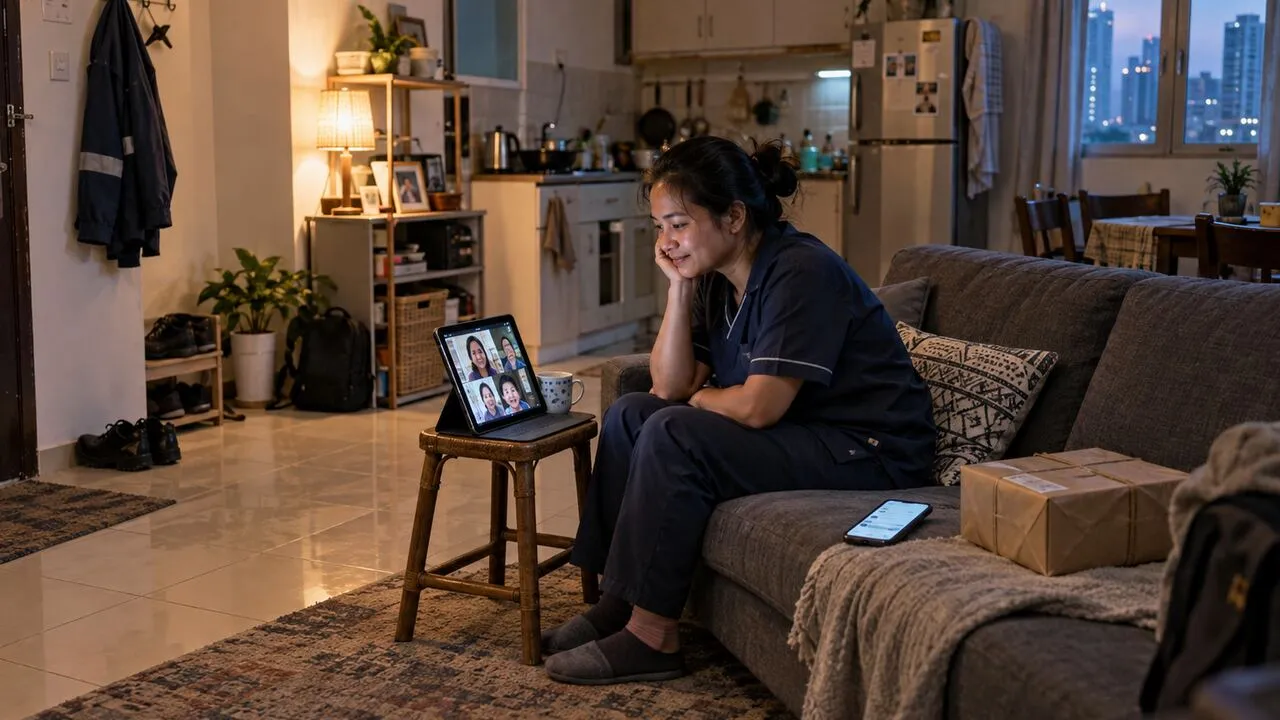
OFWs can stay connected to Philippine content, remittance services, and important accounts without treating every problem as a VPN problem. First confirm whether a service permits access where you live, then protect the connection used for sensitive logins, and keep a Philippine number or another recovery method working. A VPN helps on shared networks, but it cannot create content rights, reverse a transfer, or recover an account by itself.
Three different problems often look like one
A video that will not play, a remittance app that requests another identity check, and an email login that sends a code to an inactive SIM can all appear as “access problems.” They have different causes.
Streaming catalogs follow licensing and account-region rules. Financial services apply identity, fraud, and destination-country controls. Email, social, government, and mobile accounts depend on their own recovery settings. Changing a network route may affect what location a service sees, but it does not change a subscription contract, identity record, or phone number attached to an account.
Diagnose the layer before changing anything. Check the service status, its terms for your current country, the account region, and whether the device clock and app are current. For a broader explanation of why catalogs vary, see how regional streaming libraries work.
Keep home content familiar without bypassing the rules
Philippine news, sports, radio, and entertainment can make a long shift abroad feel less distant. Start with the publisher’s official app or site and check whether it offers an international feed, overseas subscription, replay, or licensed channel in your country. These options are usually more dependable than repeatedly changing settings when rights differ by location.
If playback fails, separate a rights restriction from an ordinary connection fault. Try the official help page, update the app, sign out and back in, and compare Wi-Fi with mobile data. Do not assume a VPN guarantees access: services can enforce account-country, payment, or licensing rules independently, and their policies may change.
Treat every remittance login like a financial handoff
Before sending money, confirm the recipient through a channel you already trust. Recheck the full name, destination account or wallet, amount, currency, fees, and expected delivery time inside the official app. A message saying a relative has a “new number” is a reason to pause, not a reason to hurry.
Open the remittance provider directly from a saved app or bookmark. Avoid links in unsolicited texts, social messages, or search ads. Use a unique password and the strongest verification method the provider supports. Never share a one-time code, screen-sharing session, or remote-control access with someone claiming they need it to release a transfer.
For the Philippine end of a transfer, check the payout company, bank, electronic-money issuer, or money service business in the Bangko Sentral ng Pilipinas Verifier. The BSP describes the tool as a way to confirm whether an institution is registered with or supervised by it; it is a useful identity check, not a guarantee that a transaction is risk-free. If a name is missing, do not immediately label it a scam—ask the provider which Philippine entity handles the payout and which regulator oversees it, then verify that answer through the regulator’s official site.
Save the receipt and reference number, then verify arrival with the recipient. If the destination details are wrong or the transfer looks unfamiliar, contact the provider through its official support route immediately. A VPN encrypts the local network path; it does not inspect the recipient or approve the transaction. The same boundary applies to online banking while abroad.
Your Philippine number is part of your identity stack
Many overseas account failures begin months earlier, when a prepaid SIM expires or a phone is replaced without moving recovery methods. Make an inventory of the accounts that still send codes to your Philippine number: primary email, banking, remittance, government, mobile wallet, and messaging services.
Where available, add a second recovery channel, save backup codes offline, and use an authenticator or passkey instead of relying only on SMS. Keep the provider’s official support details and the identity documents it requires for recovery in a secure place. Never store backup codes in the same unlocked phone that receives your login prompts.
Test recovery while you still have access. Confirm that the backup email works, that the number can receive messages abroad, and that a trusted device is still listed. If you plan to stop using a number, move every critical account before the line is released to someone else.
Use a VPN for the connection layer
Housing Wi-Fi, staff accommodation, cafés, airports, and shared family networks are convenient but not private. A VPN encrypts traffic between your device and the VPN server, reducing what people on the local network can inspect or alter. Connect before opening email, a remittance app, or private documents on a network you do not manage.
Lubi VPN supports iPhone, Android, macOS, and Windows and is optimized around Asia-Pacific connectivity. It does not retain browsing content, complete URLs, or traffic payloads; limited connection metadata may be kept for operational, security, and abuse-prevention purposes, ordinarily for no more than 90 days. That connection protection complements HTTPS and account verification rather than replacing them.
A routine for payday and the days between
On payday, use a device you control, update the remittance app, connect through mobile data or a protected trusted connection, and check every destination field before confirming. Afterward, keep the receipt and wait for independent confirmation from the recipient.
Between transfers, review recovery details, remove devices you no longer own, update important apps, and turn off automatic joining for unknown Wi-Fi. If a login prompt, transfer request, or family emergency arrives unexpectedly, verify it through a second channel. The goal is not to make overseas life frictionless; it is to prevent one lost number, unsafe network, or rushed message from cutting you off from home.